Buy Businesses, Not Stocks: The Mindset That Builds Long-Term Wealth
The World Wants You to Buy and Sell Stocks
Every day, investors are surrounded by advice.
“Buy this stock.”
“Sell that stock.”
“Target price ₹2,500.”
“Book profits now.”
“This stock could double in six months.”
Financial television, newspapers, brokerage reports, YouTube channels, Telegram groups, WhatsApp forwards, and social media all seem obsessed with one thing—trading stocks.
Very few encourage you to think about owning businesses.
That may sound like a minor difference in terminology, but it changes the way people invest.
The stock market is merely a marketplace where ownership changes hands every day. Real wealth, however, is created by businesses that develop products, serve customers, innovate continuously, generate profits, reinvest intelligently, and compound earnings over many years.
Unfortunately, many investors never make that mental transition.
They spend years trading stock symbols without ever asking whether they would genuinely want to own the business behind those symbols.
Perhaps that is why so many people constantly search for the next winning stock while so few patiently participate in the growth of exceptional companies.
The language we use shapes the way we think. If we constantly tell ourselves that we are buying stocks, our attention naturally shifts towards stock prices. If we remind ourselves that we are buying ownership in businesses, our focus begins to shift towards customers, products, management, profits, competitive advantages, and long-term growth.
That single change in perspective separates speculation from investing.
It also explains why many investors struggle to hold a wonderful company for three, five, or even ten years, despite knowing that building a great business often takes decades.
Perhaps we’ve been taught to monitor the wrong thing.
Instead of asking, “What will this stock do next week?”, maybe we should ask, “What could this business become over the next decade?”
This philosophy closely reflects Warren Buffett’s long-standing principle that investors should think like business owners rather than stock traders, a lesson repeated throughout Berkshire Hathaway’s shareholder letters.
Why You Should Buy Businesses, Not Stocks
Ask almost anyone why they bought a particular stock and you’ll probably hear one of these answers.
- “It looks ready for a breakout.”
- “Analysts upgraded the target price.”
- “Everyone is buying it.”
- “The chart looks bullish.”
- “It could double from here.”
Notice something interesting.
None of those answers mention the business.
Rarely do we hear investors say:
- “The company has outstanding capital allocation.”
- “Management has consistently created shareholder value.”
- “Its competitive advantage is strengthening every year.”
- “The business still has decades of growth ahead.”
- “I’d happily own this company even if the stock market closed for five years.”
Yet these are precisely the questions that matter most.
A share is not a lottery ticket.
It is not a betting slip.
It is not simply a ticker symbol flashing red and green throughout the trading day.
A share represents a fractional ownership interest in a real business.
When you purchase even a single share, you become one of the company’s owners. Your ownership may be tiny, but the principle remains exactly the same.
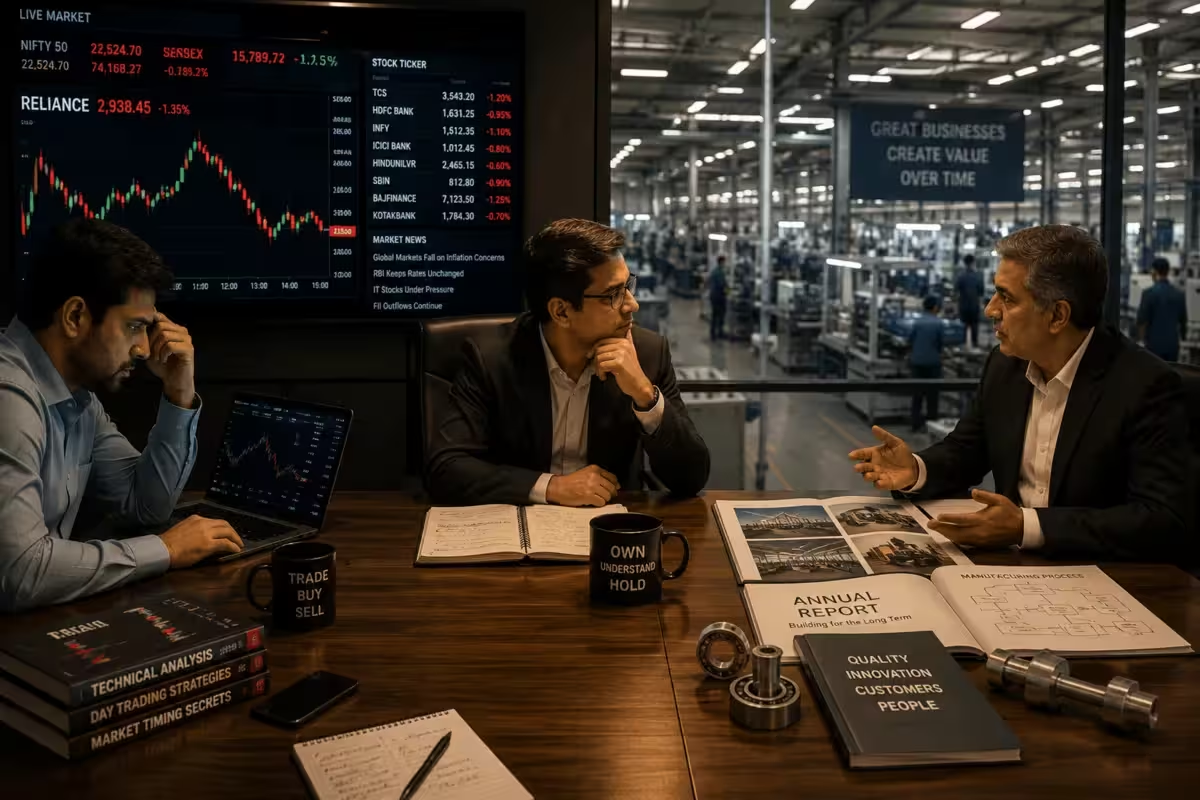
Imagine partnering with a successful local manufacturing business.
Would you decide to sell it because someone offered 5% more this month?
Would you panic because business slowed slightly during one quarter?
Would you abandon years of careful planning simply because another factory appeared more fashionable?
Of course not.
You would examine whether customers remained loyal, profits continued growing, management allocated capital wisely, and future opportunities still looked promising.
Public companies deserve exactly the same approach.
The only difference is that the stock market conveniently tells you a new price every second.
Unfortunately, that constant stream of prices often distracts investors from the thing they actually own.
The stock market quotes a price every second.
A business reveals its value only over time.
The Financial Industry Sells Activity, Not Ownership
There is a reason why long-term business ownership receives so little attention.
It isn’t exciting.
Buying a wonderful company and patiently holding it for five or ten years rarely creates daily headlines.
Constant activity does.
Brokerages benefit when investors trade frequently.
Financial news channels need fresh stories every day.
Analysts are expected to publish new recommendations.
Content creators compete to predict the market’s next move.
Social media rewards excitement far more than patience.
Hardly any participant is rewarded for saying:
“This is an exceptional business. Buy it at a sensible valuation and then allow management to create value over the next decade.”
That advice is too quiet.
Too simple.
Too patient.
Ironically, history suggests that patient ownership of outstanding businesses has created far more wealth than constantly chasing the market’s latest idea.
Why Nobody Talks About Holding for Three, Five, or Ten Years
Listen carefully to most conversations about investing.
You’ll hear endless discussions about what a stock might do tomorrow, next week, or after the next quarterly results.
You’ll rarely hear someone ask a much more meaningful question:
“Where could this business be five or ten years from now?”
That silence is surprising because businesses don’t become exceptional overnight.
Factories aren’t built in a quarter.
Brands aren’t created in six months.
Customer loyalty isn’t earned in a single financial year.
Competitive advantages are usually built through years of disciplined execution.
Yet many investors expect the stock price to fully recognise all of that progress almost immediately.
That expectation is neither realistic nor supported by market history.
The greatest businesses often spend years quietly strengthening themselves before the market fully appreciates what they have become.
Patient investors understand this.
Impatient investors usually don’t stay around long enough to benefit from it.
Businesses grow gradually.
Markets eventually notice.
Three Years Isn’t Long-Term
Many investors proudly describe themselves as long-term investors.
Then something curious happens.
If the share price remains quiet for twelve months, they become restless.
After two years, they begin questioning their original research.
By the third year, many conclude that the investment has “failed.”
Often, no.
Revenue may have continued growing.
Profits may have improved.
Cash flows may have strengthened.
Management may have continued executing its long-term strategy exactly as planned.
The only thing that has truly deteriorated is the investor’s patience.
Three years is not particularly long in the life of an outstanding business.
Neither is five.
Even ten years may represent only one chapter in the story of a company that could continue creating value for decades.
Compounding doesn’t work according to our personal timetable.
It rewards investors who allow exceptional businesses enough time to compound their earnings, expand their competitive advantages, and allocate capital intelligently.
Time is not the enemy of a great business.
It is one of its greatest competitive advantages.
Think Like the Owner of a Private Company
Imagine that instead of buying shares listed on the stock exchange, you purchased 100% ownership of a successful private manufacturing company.
The business continues attracting new customers.
Revenue increases every year.
Margins improve steadily.
Debt declines.
Cash generation becomes stronger.
Would you suddenly decide to sell the company because another business owner claimed his factory might perform better over the next six months?
Probably not.
You would continue owning a thriving business because its long-term prospects remain attractive.
Now consider what happens in the stock market.
Many investors willingly sell excellent businesses—not because anything has deteriorated—but because another stock appears more exciting.
The stock market constantly tempts investors to exchange quality for activity.
That temptation has probably destroyed more long-term wealth than many market crashes.
Stock traders chase ticker symbols.
Business owners participate in decades of value creation.
| Trader’s Mindset | Business Owner’s Mindset |
|---|---|
| What will the stock do next week? | Where will this business be in ten years? |
| Daily price movements | Long-term business progress |
| Constant buying and selling | Patient ownership |
| Following market sentiment | Following business fundamentals |
| Looking for excitement | Looking for compounding |
The remarkable thing is that both investors can own exactly the same company.
Only their mindset is different.
One constantly watches the ticker.
The other quietly watches the business.
The Market Often Rewards Patience Last
One of the most frustrating realities of investing is that business performance and stock price performance rarely move together in the short term.
A company may spend years improving its operations before the market finally recognises its true value.
That delay often causes investors to lose confidence at precisely the wrong moment.
Ironically, the market frequently rewards patient investors only after testing whether they truly deserve that reward.
Those who focus only on today’s share price often mistake temporary neglect for permanent failure.
Those who focus on business performance recognise something entirely different.
Sometimes the business is progressing far faster than the stock price suggests.
Markets may overlook a great business for years.
Eventually, they rarely ignore it forever.
Short-Term Price Movements Rarely Tell the Whole Story
Every listed company has two stories unfolding at exactly the same time.
The first story is visible every second.
It is the share price.
The second story unfolds much more quietly.
It is the business itself.
Unfortunately, investors spend far more time watching the first story than understanding the second.
Share prices move for countless short-term reasons.
- Economic news.
- Interest rate decisions.
- Foreign institutional investor flows.
- Political events.
- Global market sentiment.
- Algorithmic trading.
- Temporary optimism or fear.
Very few of these factors reveal whether the underlying business has actually become stronger.
Businesses grow through an entirely different set of drivers.
- Consistent revenue growth.
- Improving profit margins.
- Higher return on capital.
- Growing free cash flow.
- Prudent capital allocation.
- Expanding competitive advantages.
- Capable and trustworthy management.
These two timelines rarely move together.
Sometimes the stock price runs far ahead of the business.
Sometimes the business quietly runs far ahead of the stock price.
The first situation excites speculators.
The second rewards long-term investors.
Markets often recognise value late.
Patient investors benefit from that delay.
Ask Better Questions Before Buying a Business
Many investment decisions begin with the wrong questions.
“What is the target price?”
“Will it double this year?”
“What do analysts recommend?”
Those questions may satisfy curiosity, but they rarely improve investment outcomes.
A business owner would ask a completely different set of questions.
- Would I be happy to own this business if the stock market closed for five years?
- Does the company have durable competitive advantages?
- Can management allocate capital wisely?
- Will demand for its products likely increase over the next decade?
- Is the balance sheet financially strong?
- Can earnings continue compounding over long periods?
- Am I buying this business at a sensible valuation?
Notice that none of these questions require predicting tomorrow’s stock price.
Instead, they encourage investors to understand the business they intend to own.
That small change in thinking often leads to dramatically different investment decisions.
Thinking Like an Owner Changes Everything
Once you begin thinking like a business owner rather than a stock trader, several behavioral changes happen almost automatically.
You stop refreshing stock prices every hour.
You become less interested in market gossip.
Temporary market declines begin to look like opportunities instead of disasters.
You spend more time reading annual reports than watching financial television.
You start evaluating management decisions instead of analyst opinions.
Most importantly, your confidence begins to come from the business itself rather than from its daily share price.
That is an enormous psychological advantage.
Markets can remain irrational for surprisingly long periods.
Strong businesses, however, tend to keep creating value regardless of whether the market immediately notices.
Confidence built on stock prices disappears quickly.
Confidence built on business fundamentals lasts much longer.
The Greatest Investments Were Rarely Great Trades
History’s greatest investments rarely looked extraordinary in their early years.
Many outstanding companies spent years moving sideways.
Others experienced painful corrections despite continuing to improve as businesses.
Some even disappointed investors searching for quick profits.
Yet patient shareholders who concentrated on business performance rather than market excitement eventually benefited from years—even decades—of uninterrupted compounding.
Very few fortunes have been built by constantly finding the next exciting stock.
Many fortunes have been built by recognising an exceptional business early and then having the discipline to stay invested while that business continued creating value.
That distinction is easy to overlook because successful investing often appears deceptively uneventful.
There are no daily celebrations.
No dramatic predictions.
No constant buying and selling.
Just years of patiently allowing capable management teams to do what they do best—build better businesses.
Outstanding investments usually begin as ordinary decisions.
Time is what makes them extraordinary.
Final Thoughts
The next time you hear someone confidently say, “This stock will double,” pause for a moment.
Ask yourself a different question.
“What kind of business am I actually being invited to own?”
That single question can completely change the way you invest.
When you stop thinking like a trader and start thinking like a business owner, your priorities begin to change naturally.
You become less concerned about tomorrow’s share price and more interested in next year’s annual report.
You stop chasing market excitement and begin appreciating business execution.
You no longer measure success by how frequently you trade.
You measure it by how well the businesses you own continue creating value over time.
That doesn’t mean every investment should be held forever.
Businesses change.
Industries evolve.
Management teams make mistakes.
Competitive advantages can disappear.
When the original investment thesis breaks down, investors should reassess their ownership with complete objectivity.
Long-term investing is not about refusing to sell.
It is about refusing to sell for the wrong reasons.
Rather you need to know when to sell your business!
Selling because the business has fundamentally deteriorated is rational.
Selling because the market has become impatient is something entirely different.
The goal isn’t to own a stock for ten years.
The goal is to own a great business for as long as it deserves your capital.
Perhaps that is the biggest misunderstanding in modern investing.
People often ask, “How long should I hold this stock?”
The better question is, “How long can this business continue creating value?”
Those are not the same question.
The first focuses on the market.
The second focuses on the business.
And businesses—not stock tickers—are what ultimately create wealth.
If there is one idea worth remembering from this article, let it be this:
Don’t invest in a stock because you expect the price to rise.
Invest in a business because you believe the company will become more valuable over time.
Share prices will always fluctuate.
Opinions will always change.
Analysts will continue revising their forecasts.
Financial media will keep searching for the next headline.
Through all that noise, successful investors quietly focus on something far more enduring.
They own businesses.
They understand those businesses.
And they allow time to do what time has always done best.
Compound value.
The stock market exists to facilitate ownership.
It is not the destination.
The destination is owning businesses that continue becoming stronger, more profitable, and more valuable year after year.
That is how lasting wealth has always been created.
And that is why investors should stop asking how long they should hold a stock—and start asking whether they have found a business worth owning for many years to come.
People often say that the best investment portfolios belong to those who have passed away—or those who simply forgot they had one.
The lesson isn’t about death. It’s about patience. Exceptional businesses don’t need constant supervision. They need time to grow, compound, and create lasting wealth for patient owners.
Did You Read The Disclaimer?
Not a SEBI-Registered Research Analyst or Investment Adviser
I am not a SEBI-registered Research Analyst or Investment Adviser. Raj & Co is an independent educational and informational website. All articles, views, opinions, observations, analyses and other content published on this website are provided solely for general informational and educational purposes.
Nothing published on this website constitutes investment advice, financial advice, research advice, a research report, a recommendation, solicitation, offer, endorsement or invitation to buy, sell, subscribe to, hold or otherwise deal in any security, financial product or investment strategy. The content is not tailored to any individual’s financial circumstances, investment objectives, risk tolerance or other personal circumstances.
Any discussion of a company, security, market, investment strategy, price, valuation, historical performance or other investment-related matter is intended solely for educational discussion and should not be interpreted as a recommendation or prediction of future performance. References to particular securities or investments do not constitute recommendations to buy, sell, or hold them.
I may personally buy, sell, hold or change my views or positions in securities at any time. Such personal transactions or changes in views do not constitute recommendations to readers. Where I disclose such positions or changes, the disclosure may occur after a transaction has been executed and may not be immediate.
Investment in the securities market is subject to market risks. Past performance is not indicative of future results. Readers should conduct their own independent research and due diligence and consider their own financial circumstances, investment objectives and risk tolerance before making any investment decision. If personalized financial advice is required, consult a financial adviser or other professional appropriately registered with SEBI.
No representation or warranty is made regarding the accuracy, completeness, timeliness or reliability of any information published on this website, and no responsibility is accepted for any loss arising from reliance upon such information to the extent permitted by applicable law.
SEBI’s investor education initiatives emphasize informed investing, financial literacy, risk awareness, and disciplined long-term wealth creation.
E & O E.