Stock Price Targets: Finance or Fortune-Telling?
Introduction
Open any financial news website, switch on a business television channel, browse social media, or log in to your brokerage account, and you will almost certainly see a stock price target. One analyst expects a stock to reach ₹2,500 within twelve months. Another cuts the same company’s target to ₹2,100 after the quarterly results. A week later, someone else raises it again.
These targets are usually presented with a level of confidence that can make them look much more certain than they really are. There is a number, a time frame, and often a detailed valuation model behind it. Investors then use that number to decide whether to buy, sell, or wait, as though the analyst has some special ability to see where the stock will trade in the future.
But there is a simple question that does not get asked nearly enough.
If analysts can accurately predict future stock prices, why do their price targets change so frequently?
The reality is that no analyst, fund manager, television expert, or economist can consistently know where a stock will trade a few months from now. Too many things can change between the day a target is published and the day it is supposed to be reached. Valuation models can help us think about value, but they cannot tell us what the market will think, what investors will feel, or what surprise is waiting around the corner.
That matters to long-term investors. Investing is not about guessing next year’s stock price. It is about finding good businesses, understanding how they make money, deciding what they are worth, and staying invested as long as the business continues to justify your ownership.
Imagine reading a newspaper in January 2026 that confidently predicted the exact closing price of every major stock on December 31, 2026. Would you believe it? Probably not. Yet every day, investors give considerable weight to stock price targets that are making a broadly similar claim, even if the claim is wrapped in spreadsheets, financial models, and professional terminology.
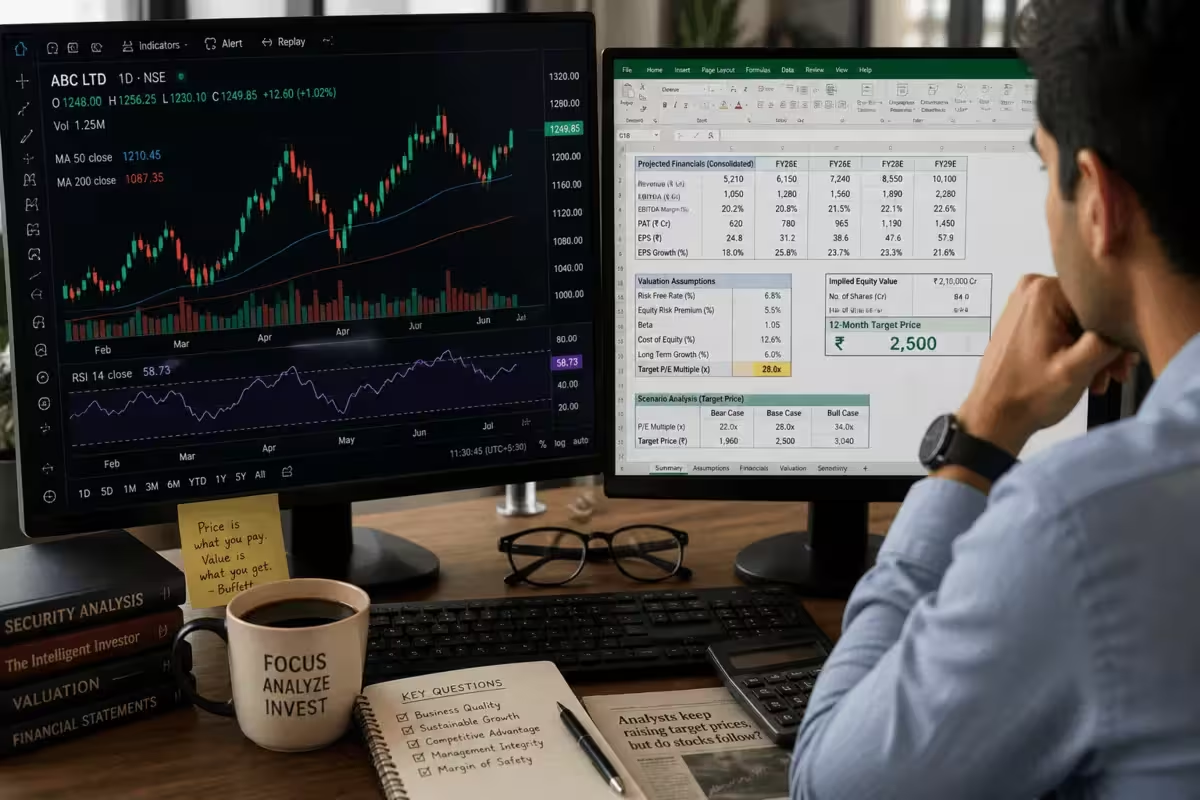
Nobody Knows Next Year’s Stock Price
Every stock price target starts with assumptions about the future. Analysts estimate future revenue, earnings, profit margins, cash flows, interest rates, and valuation multiples before arriving at a target price. The work behind those estimates can be detailed and serious. But the assumptions are still assumptions.
The future rarely behaves like a spreadsheet. Inflation can move differently from expectations. Interest rates can change. Governments can introduce new rules. Geopolitical tensions can appear suddenly. Consumer behavior can shift. Technology can disrupt an industry faster than expected. Even a well-run company can run into a problem that nobody saw coming a year earlier.
Company management teams know this very well. They know their own businesses better than outside analysts do, yet they are still cautious about making precise long-term forecasts. They can control some things, influence others, and predict a few more. They cannot control the entire environment in which the business operates.
Expecting an analyst to know the exact stock price months in advance is therefore asking for something that nobody can reliably provide. And the stock price is harder to predict than the business itself.
Two companies can report similar financial results and still see very different stock-price reactions. One may rise sharply while the other falls because expectations were different, market sentiment was different, liquidity was different, or investors had already priced in a different outcome. The stock price reflects the business, but it also reflects what thousands or millions of market participants currently expect from that business.
Businesses create value. Markets decide when—and at what price—to recognize that value.
That distinction is important. You can often make a reasonable assessment of how a good business might perform over the next several years. You cannot make the same claim about where the market will price its shares on a particular date next year.
Businesses Are Predictable. Stock Prices Are Not.
This is one reason I would rather spend time studying a business than trying to predict its share price. A business leaves behind evidence. It reports revenue, profits, cash flow, debt, capital allocation, customer growth, margins, and other operating numbers. You can study how those numbers have changed and try to understand why.
Questions such as these deserve an investor’s attention:
- Is the company’s revenue growing consistently?
- Are profit margins improving or deteriorating?
- Does the business generate healthy free cash flow?
- Does it possess a durable competitive advantage?
- Is management allocating capital wisely?
- Can the business continue growing over the next decade?
These questions do not guarantee that an investment will work. Nothing does. What they do is keep your attention on the things that actually determine whether a business can create value and wealth over time.
Now compare that with asking whether a stock will reach ₹2,500 or ₹3,000 in the next few months. At that point, you are moving away from understanding the business and toward forecasting the market. The exact price can depend as much on expectations and sentiment as on the company’s operating performance. That is why two analysts can look at the same company, make sensible assumptions, and still produce very different targets.
This is also why great investors think like business owners rather than stock traders. An owner wants to know whether the business is becoming stronger year after year. An owner does not wake up every morning wondering whether an analyst has raised the target price by ₹200.
If you understand the business well enough to own it for ten years, next year’s target price becomes far less important.
Price Targets Create an Illusion of Precision
There is something else about price targets that deserves attention: the false sense of precision they create.
An analyst does not usually say, “I think this stock is worth around ₹2,500.” The report may instead give a target of ₹2,473 or ₹2,618. A number like that looks scientific. It gives the impression that the analyst has calculated the future to the last few rupees.
But does the future really work that way?
Of course not. A valuation model depends on assumptions about revenue growth, operating margins, capital expenditure, taxes, interest rates, discount rates, and many other variables. Change one assumption and the answer can change. Change several, and the target can move a long way.
Take a simple example. Suppose an analyst expects a company to grow its earnings by 15% a year. What happens if actual growth is 12% instead? What if it is 18%? Over several quarters, that difference can become meaningful, and the value derived from the model can change substantially. The same is true of interest rates. A relatively small change in rates can put pressure on valuations across an entire sector even when the underlying businesses have not suddenly become worse.
None of this makes valuation models useless. Quite the opposite. A good valuation model forces you to think clearly about the assumptions you are making and the value you are assigning to a business. The mistake is taking the final number and treating it as though it were a forecast of where the market will trade at some future date.
A valuation is an estimate of value. A price target is often mistaken for a prediction of the future. The two are not the same.
Markets have a way of reminding investors of this distinction. No matter how neat the spreadsheet looks, the real world does not have to cooperate with it. Investing is ultimately a game of probabilities, not certainties.
Why Do Analysts Keep Changing Their Price Targets?
If you have followed the markets for a while, you have probably seen the pattern many times. A company announces quarterly results, and analysts revise their targets. The central bank changes interest rates, and targets move again. Management changes its guidance, commodity prices move, the currency moves, or a new regulation appears, and the models are updated once more.
That does not necessarily mean the analyst was careless. A valuation depends on assumptions, and new information can change those assumptions. Updating a target when the underlying facts change is actually the sensible thing to do.
The problem comes when investors treat every revision as a fresh buy or sell signal.
A higher target does not automatically make the business a better investment. A lower target does not automatically make it a bad one. The business may not have changed nearly as much as the valuation assumptions have. Sometimes the only thing that has changed is what the analyst expects from earnings, rates, or the market multiple.
So when a target changes, look at the reason. Has the company’s competitive position improved? Has the balance sheet become stronger? Are earnings more durable than before? Has management made better use of capital? Or has the analyst simply changed an assumption about the environment?
Instead of asking, “Has the target price changed?”, ask, “Has the business changed?”
That is a much more useful way to think. Businesses create long-term wealth through growth, profitability, and sensible capital allocation. An analyst increasing a target price by 10% does not create a single rupee of that wealth.
Are Stock Price Targets Reliable?
The honest answer is: they are reliable as opinions, not as predictions. A stock price target is an analyst’s estimate of what a business may be worth under a particular set of assumptions at a particular point in time. It is not a promise about where the market will trade the stock in the future.
Sometimes a target turns out to be remarkably close to the eventual market price. In other cases, something happens that makes the original target almost irrelevant within a few months. Neither outcome should surprise us. New information keeps entering the market, and nobody knows in advance what that information will be.
Research on analyst forecasting also suggests that professional estimates can still have value without being infallible. Analyst forecasts can provide useful information, particularly over shorter horizons, but their predictive advantage becomes less compelling as the forecast horizon gets longer.
That is why I find a different question more useful than asking whether a target is right or wrong: What assumptions led to this valuation?
A target price should start your research—not end it.
Should You Buy a Stock Based on a Target Price?
Buying a stock simply because an analyst sees 20% upside is not, by itself, a sound investment strategy. You are not buying a ticker symbol. You are becoming a part-owner of a business. A higher target does not automatically make that business more attractive, just as a lower target does not automatically make it one to avoid.
Before investing, ask yourself questions that a price target cannot answer:
- Do I understand how this business makes money?
- Does it possess a durable competitive advantage?
- Can earnings grow consistently over the next five to ten years?
- Is management competent, honest, and shareholder-friendly?
- Am I paying a reasonable price relative to the business’s long-term prospects?
These questions take more work than reading a brokerage report, but they give you something much more useful: your own understanding of the investment. The stock-investing checklist covers many of the financial and qualitative factors investors can examine before making an investment decision.
There is also a practical reason not to build your conviction around somebody else’s target. Suppose you buy because an analyst expects a stock to reach ₹3,000. A few months later, the analyst cuts the target to ₹2,400. What happens to your conviction? If the business has not changed, nothing about the investment thesis may have changed. But if the thesis was built around the target price, you may suddenly feel that you need to sell.
That is not conviction. That is dependence on somebody else’s forecast.
Invest because you understand the business—not because someone predicts a higher stock price.
How Accurate Are Brokerage Recommendations?
Brokerage research serves a useful purpose. Research analysts spend considerable time studying companies, speaking with management teams, analysing financial statements, following industries, and building valuation models. Their reports can contain information and perspectives that are genuinely useful to investors.
But a detailed report does not remove uncertainty. The SEC’s investor guidance on analyst recommendations also highlights the importance of understanding analysts’ ratings, disclosures, and potential conflicts of interest. Beyond those issues, there is a more basic problem: the world keeps changing after the report is published.
Economic conditions change. Competitors innovate. Customers change their preferences. Governments change rules. Commodity prices move. Currencies move. Geopolitical events happen. A company can also make a decision that was simply not part of the analyst’s original assumptions.
So I would treat a brokerage report as one source of information, not as the final authority. Read it to understand another person’s thinking. Use it to spot risks, assumptions, questions, or details you may have missed. Then do your own work.
Independent thinking is one of the biggest advantages an individual long-term investor can have. You do not have to ignore professional research. You just should not become dependent on it.
The best investors don’t follow every recommendation. They build enough knowledge to evaluate those recommendations for themselves.
Are Stock Price Targets Useful?
Yes—but only when you understand what they are and, just as importantly, what they are not.
A stock price target is an analyst’s view of fair value under a specific set of assumptions. That can be useful. It gives you something to examine, question, and compare. It can also show you how another investor or analyst is thinking about the business.
What it cannot do is guarantee that the market will eventually trade at that price. It cannot guarantee that the assumptions will prove correct either.
Used sensibly, target prices can make you think about valuation and help you understand different ways of looking at a company. Used blindly, they can encourage impulsive buying, premature selling, and frustration when the market does something completely different from what the report suggested.
The number itself is not the problem. The problem is what investors expect that number to tell them.
Price targets are reference points, not destinations.
What Great Investors Focus On Instead
The world’s most successful long-term investors have generally spent much more time understanding businesses than predicting where a stock will trade next quarter or next year. The hard part is learning to separate useful evidence from market noise and to build conviction through a disciplined investment process.
Instead of asking, “Where will this stock be next year?“, ask questions such as:
- Is this business becoming stronger every year?
- Does it enjoy a sustainable competitive advantage?
- Can it continue compounding earnings over the next decade?
- Is management acting in the best interests of shareholders?
- Am I buying with an adequate margin of safety?
Notice what these questions have in common. None of them requires you to predict the exact stock price a year from now. They are about the quality of the business, its ability to withstand problems, its prospects for growth, and the price you are paying for that future.
An exceptional business can create considerable shareholder wealth even while its stock price behaves badly for months or even years. The opposite is also true. A stock can rise sharply without the underlying business becoming meaningfully better.
Markets are voting machines in the short run and weighing machines in the long run. Short-term prices react to news, emotions, expectations, liquidity, and countless other factors. Over longer periods, business performance matters much more.
Don’t spend your life trying to predict the market’s next move. Spend it learning how to recognise extraordinary businesses.
Who Audits the Analysts?
Most professions are measured in some way. Companies are judged by their financial performance. Mutual funds are judged by their long-term returns. Credit rating agencies face scrutiny when highly rated borrowers default. Even weather forecasts can be compared with what actually happened.
That raises an interesting question: who measures the long-term accuracy of stock price targets?
Imagine if every analyst’s 12-month price target were publicly tracked and put into a simple scorecard. Investors could then see how often the target was actually reached within the stated time frame, how often it was missed, and how often it was changed before the forecast period ended.
Interestingly, regulators have recognised the value of putting price targets into historical context. SEBI’s research-analyst regulations require specified research reports containing ratings or price targets to include historical price information, allowing investors to view the security’s price history alongside the analyst’s research. But historical context is not the same thing as a proper record of forecasting accuracy. That distinction matters.
- Achieved within the forecast period.
- Missed the target.
- Revised before the target date.
- Withdrawn because the assumptions changed.
A scorecard like this would give investors a better way to judge forecasts. It would help separate targets that have historically held up reasonably well from targets that are repeatedly changed as market conditions change. More importantly, it would remind investors what a price target actually is: a forecast based on assumptions, not a fact about the future.
This is not a criticism of analysts. Predicting the future in financial markets is genuinely difficult. Economic conditions can change, competitors can move quickly, regulations can change, technology can disrupt an industry, and investor expectations can shift without warning. Revising an estimate when new information arrives is often the responsible thing to do.
Still, if investors are expected to pay attention to price targets when making investment decisions, it is perfectly reasonable to ask how those forecasts have performed over time. Better transparency around forecasting accuracy would give investors more context and make individual targets easier to judge for what they are.
Extraordinary confidence deserves equally transparent accountability. If forecasts influence investment decisions, investors deserve to know how those forecasts have performed over time.
Perhaps the most useful question is not, “What is the latest target price?” but, “How often have similar target prices proved accurate in the past?” That shifts the conversation away from certainty and toward evidence. And evidence is what investors should want in the first place.
Conclusion
Stock price targets will continue to dominate financial headlines because people naturally want certainty about the future. A single number looks simple. It looks authoritative. It gives investors something concrete to hold on to when the future is anything but concrete.
But investing does not work that way.
The future cannot be reduced to a target price. Businesses evolve, economies change, technologies disrupt industries, and markets regularly surprise even experienced professionals. No spreadsheet can fully capture all of that uncertainty.
Instead of asking whether a stock will reach a particular price next year, ask whether the business is likely to become stronger over the next five or ten years. That is a question you can actually research.
Successful investing is not about finding someone who can predict tomorrow’s stock price. It is about developing the patience, discipline, and conviction to own outstanding businesses while they continue to create value.
Finance is about analyzing businesses. Fortune-telling is about predicting prices. The most successful investors know the difference.
The next time you see a stock price target, don’t start by asking whether the number is right. Start by asking whether the business is becoming better. One question pushes you toward speculation. The other keeps you focused on the investment itself.
In investing, conviction should be earned through evidence—not borrowed from someone else’s forecast.
Frequently Asked Questions
Are stock price targets reliable?
Stock price targets are estimates based on a particular set of assumptions. They can be useful, but they should not be treated as reliable predictions of future market prices. Investors should understand the reasoning behind a target instead of relying on the number alone.
Should I buy stocks based on analyst target prices?
No single target price should determine an investment decision. Look at the company’s business quality, financial strength, competitive advantages, valuation, and long-term growth prospects before investing.
Why do analysts keep changing stock price targets?
Analysts revise target prices when new information changes their assumptions about future earnings, interest rates, economic conditions, or company performance. Changing a target when the underlying assumptions change is normal.
How accurate are brokerage recommendations?
Brokerage reports can provide useful research and insights, but no recommendation can consistently predict future market prices. They are best used as an input to your own research rather than as a substitute for it.
Are stock price targets useful for long-term investors?
They can be useful as one input into the investment process, particularly for understanding valuation assumptions. But long-term investors generally gain more from understanding the business and its long-term prospects than from focusing on short-term price forecasts.
Did You Read The Disclaimer?
Not a SEBI-Registered Research Analyst or Investment Adviser
I am not a SEBI-registered Research Analyst or Investment Adviser. Raj & Co is an independent educational and informational website. All articles, views, opinions, observations, analyses and other content published on this website are provided solely for general informational and educational purposes.
Nothing published on this website constitutes investment advice, financial advice, research advice, a research report, a recommendation, solicitation, offer, endorsement or invitation to buy, sell, subscribe to, hold or otherwise deal in any security, financial product or investment strategy. The content is not tailored to any individual’s financial circumstances, investment objectives, risk tolerance or other personal circumstances.
Any discussion of a company, security, market, investment strategy, price, valuation, historical performance or other investment-related matter is intended solely for educational discussion and should not be interpreted as a recommendation or prediction of future performance. References to particular securities or investments do not constitute recommendations to buy, sell, or hold them.
I may personally buy, sell, hold or change my views or positions in securities at any time. Such personal transactions or changes in views do not constitute recommendations to readers. Where I disclose such positions or changes, the disclosure may occur after a transaction has been executed and may not be immediate.
Investment in the securities market is subject to market risks. Past performance is not indicative of future results. Readers should conduct their own independent research and due diligence and consider their own financial circumstances, investment objectives and risk tolerance before making any investment decision. If personalized financial advice is required, consult a financial adviser or other professional appropriately registered with SEBI.
No representation or warranty is made regarding the accuracy, completeness, timeliness or reliability of any information published on this website, and no responsibility is accepted for any loss arising from reliance upon such information to the extent permitted by applicable law.
SEBI’s investor education initiatives emphasize informed investing, financial literacy, risk awareness, and disciplined long-term wealth creation.
E & O E.